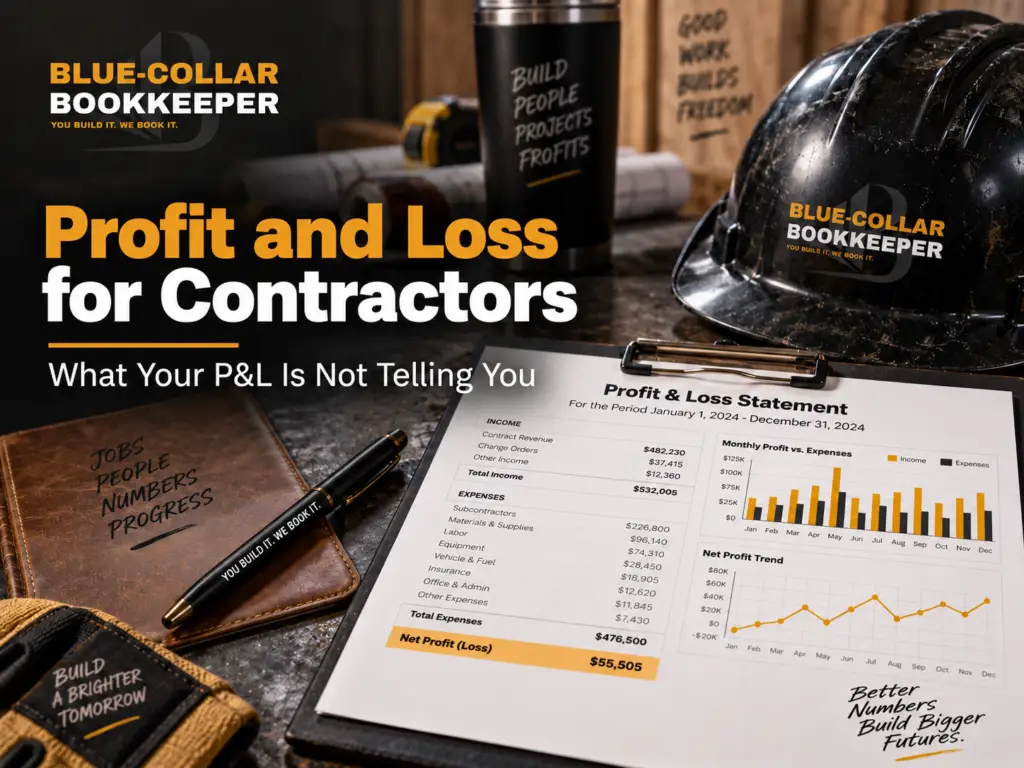
Your P&L may say the business made money, but that doesn’t mean the report is telling you the whole story.
A contractor can look at a profit and loss report, see a profit, and still feel like the business is tight on cash, underpriced, or harder to manage than it should be.
That’s frustrating.
You worked hard. The jobs got done. Money came in. The report says there’s profit.
So why does the bank account still feel thin?
The answer is usually this: your profit and loss report is useful, but it’s not the whole picture.
A P&L can help you understand revenue, expenses, gross profit, and net profit. But it may not clearly show cash flow timing, job-by-job profitability, unpaid invoices, owner draws, debt payments, tax pressure, or whether the numbers behind the report are even clean.
That’s why profit and loss for contractors needs to be looked at differently than a basic business report.
Your P&L Is Useful, But It Is Not the Whole Business
A profit and loss report shows income and expenses over a certain period of time.
That might be a month, quarter, or year.
A profit and loss report for construction business can show how much revenue came in, what expenses were recorded, and whether the business showed a profit or loss during that period.
That’s useful.
But it doesn’t automatically answer every question a contractor owner needs answered.
It may not show which jobs made money. It may not show whether customers have paid. It may not show whether materials were bought before cash came in. It may not show owner draws, loan principal payments, tax money that needs to be set aside, or old messy transactions sitting in the wrong place.
In other words, your P&L can be technically available and still not be very helpful.
The report is only useful if the books behind it are clean, current, and set up around how your contracting business actually operates.
Revenue Doesn’t Mean Profit
Revenue isn’t the same thing as profit.
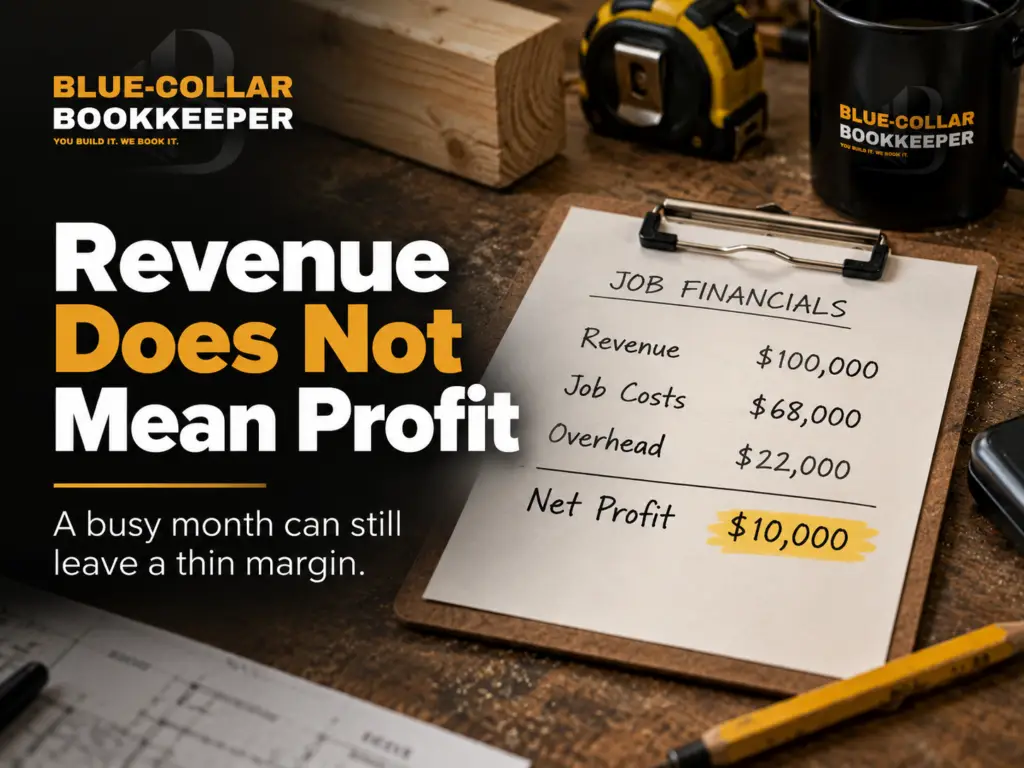
A contractor can bring in $100,000 in a month and still have a much smaller amount left after the work gets paid for.
Let’s say a contractor has a strong month:
Revenue: $100,000
Job costs: $68,000
Overhead: $22,000
Net profit: $10,000
That business brought in $100,000, but it did not make $100,000.
After materials, labor, subcontractors, equipment, fuel, insurance, office costs, software, bookkeeping, marketing, and other expenses, the actual profit was much smaller.
That doesn’t mean the month was bad. It means revenue only tells part of the story.
Revenue tells you how much money came into the business.
Profit tells you what was left after the business paid for the work.
That’s one reason clean books for contractors matter. Without clean numbers, it’s easy to confuse activity with profitability.
Gross Profit and Net Profit Aren’t the Same Thing
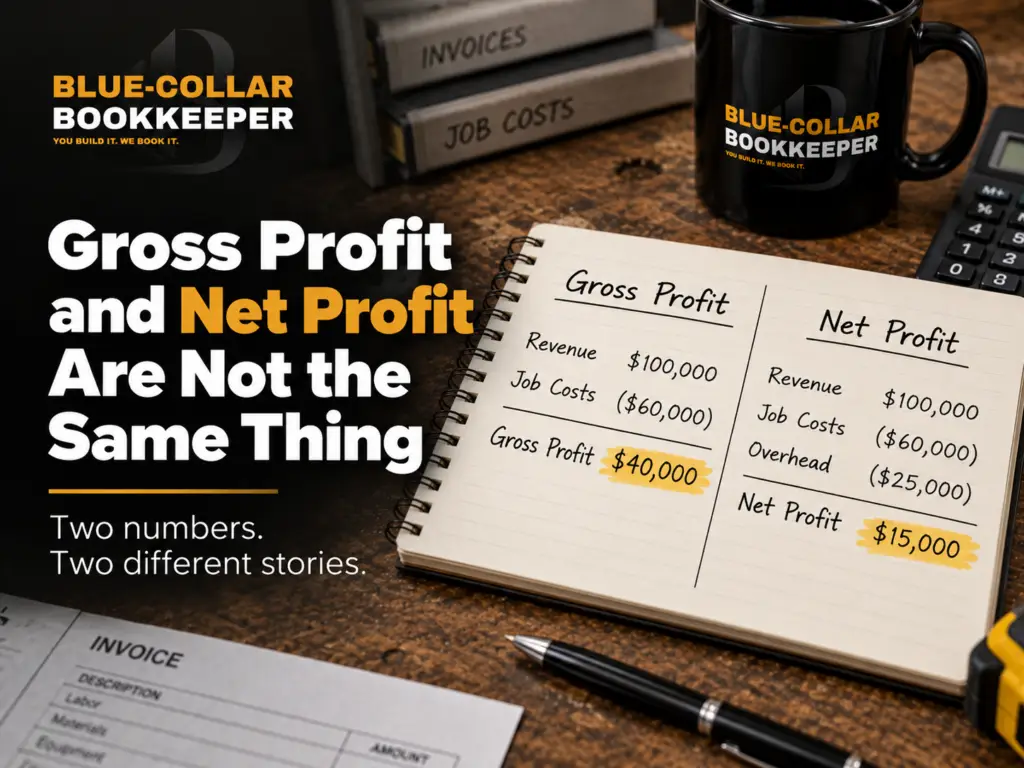
Gross profit and net profit are two different numbers, and both matter.
Gross profit usually shows what’s left after direct job costs.
For contractors, direct job costs may include materials, labor, subcontractors, equipment rentals, permits, dump fees, delivery charges, and other costs tied directly to getting the job done.
Net profit shows what is left after overhead and operating expenses are also counted.
Overhead may include insurance, office expenses, software, phones, bookkeeping, marketing, admin pay, general truck expenses, professional services, and other costs that support the business but may not belong to one specific job.
Here’s a simple way to think about it:
Gross profit shows how well the work itself performed.
Net profit shows how the whole business performed.
Both numbers matter.
A contractor might have decent gross profit but weak net profit because overhead is too high. Or the business may have weak gross profit because jobs are underpriced, materials are running over, labor is taking too long, or subcontractor costs are higher than expected.
The problem is that many contractor books blur job costs and overhead together.
When that happens, the P&L may show expenses, but it won’t clearly show what’s happening inside the work.
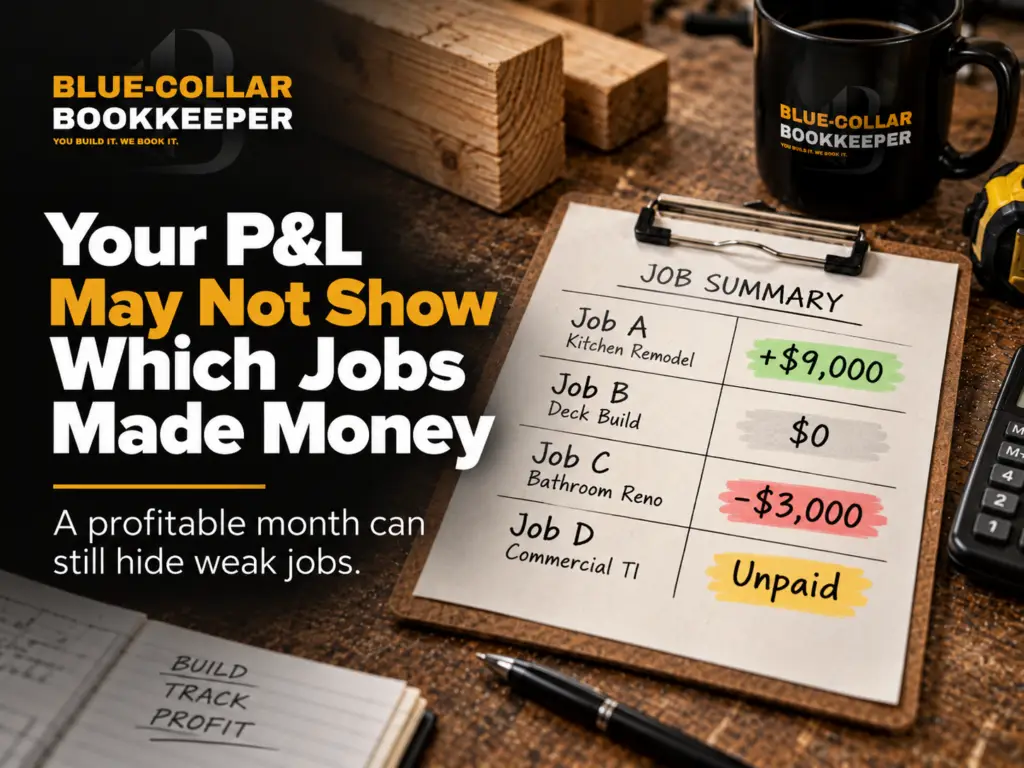
Your P&L May Not Show Which Jobs Made Money
This is one of the biggest problems with relying only on a basic P&L.
The report may show that the business made $12,000 for the month.
But that doesn’t mean every job made money.
One job may have made $9,000.
One job may have broken even.
One job may have lost $3,000.
Another job may still be unpaid.
A monthly P&L can hide those details inside the overall business total.
That’s why job costing for contractors matters. Contractors need to know which jobs are carrying the business and which ones are quietly eating into the margin.
A profitable month can still include weak jobs.
A busy schedule can still include underpriced work.
A good-looking P&L can still hide the fact that certain projects are not worth repeating.
Job costing helps break the numbers down so the owner can see what happened job by job, not just month by month.
Job Costs Can Get Buried in the Wrong Categories
A P&L is only as useful as the categories behind it.
If job costs are buried in the wrong place, the report may look complete but still fail to help the contractor make decisions.
For example:
Materials may be entered as general supplies.
Subcontractor payments may be mixed with payroll or outside services.
Equipment rentals may be buried in miscellaneous expenses.
Fuel may not be separated clearly.
Owner purchases may be mixed with business expenses.
Small job-specific costs may never get assigned to the project they belonged to.
When that happens, the P&L may technically show expenses, but it won’t show the business clearly.
A contractor needs to know whether materials, labor, subcontractors, and project costs are being tracked in a way that supports real decisions.
That connects directly to how contractors track materials, labor, and subcontractors throughout the job.
The cleaner those costs are in the books, the more useful the P&L becomes.
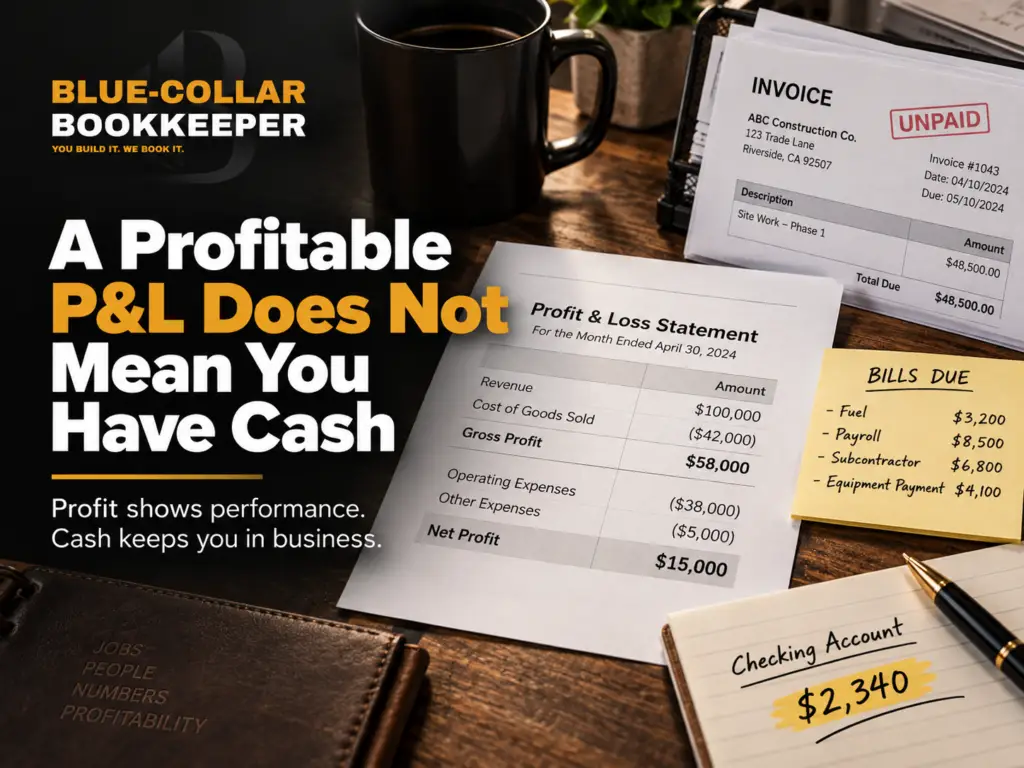
A Profitable P&L Does Not Mean You Have Cash
A contractor can show profit and still feel short on cash.
That sounds backward, but it happens all the time.
Maybe customers haven’t paid yet.
Maybe materials were paid upfront.
Maybe subcontractors had to be paid before the final invoice was collected.
Maybe loan payments hit the bank.
Maybe tax money wasn’t set aside.
Maybe owner draws pulled cash out of the business.
Maybe several jobs are profitable on paper but the timing of money coming in and going out is rough.
That’s why profit and cash aren’t the same thing.
A P&L can show profit while the bank account still feels tight. It doesn’t always show the full cash-flow pressure happening inside the business.
That’s where contractor cash flow needs to be reviewed alongside the P&L.
Profit matters.
Cash flow matters too.
Contractors need both.
Owner Draws Can Make the Bank Feel Tight
Owner draws aren’t automatically a problem.
Business owners need to get paid.
But owner draws can make the bank account feel tighter than the P&L suggests because they usually don’t show up as regular business expenses on the profit and loss report.
That can confuse owners.
The P&L may show profit, but the bank account may be lower because money was pulled out for personal use, taxes, household needs, or owner pay.
Again, that doesn’t mean the owner did something wrong.
It means draws need to be watched against cash flow, upcoming bills, taxes, payroll, subcontractor payments, and the timing of customer collections.
A contractor shouldn’t rely on the P&L alone to decide how much cash can safely come out of the business.
The P&L is part of the picture.
The bank account, open invoices, bills due, taxes, debt payments, and upcoming job costs matter too.
Debt Payments May Not Appear the Way You Expect
Debt can also make the P&L confusing.
A contractor may have truck loans, equipment financing, business loans, credit cards, or other debt payments coming out of the bank account.
Some of those payments may not show up on the P&L the way an owner expects.
Interest may show as an expense.
Principal payments may reduce the loan balance instead of showing as a normal expense on the P&L.
But both still affect cash.
So the business may show profit while cash leaves the bank for debt payments.
This is another reason contractors shouldn’t use the P&L by itself as the only health check for the business.
The P&L helps show whether the business is profitable.
It does not always show where cash went.
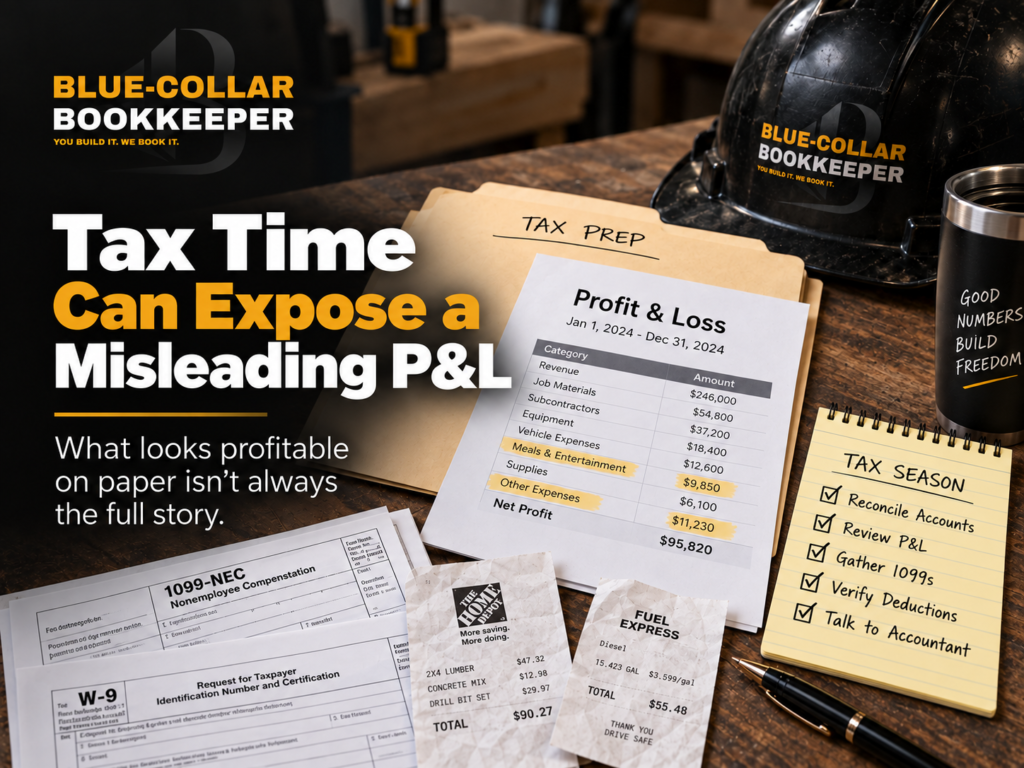
Tax Time Can Expose a Misleading P&L
Tax time has a way of exposing bookkeeping problems.
If income is recorded incorrectly, expenses are in the wrong categories, subcontractor payments are unclear, receipts are missing, and accounts aren’t reconciled, the P&L may not be ready for a tax professional.
A report can exist and still not be clean.
Contractors need books that are organized before tax season gets close. That means income, expenses, subcontractor records, 1099 information, receipts, bank activity, and QuickBooks categories should be cleaned up before the pressure hits.
That’s why tax-ready books matter.
The goal isn’t just to hand over a report.
The goal is to hand over numbers that are easier to trust.
A Messy QuickBooks File Can Make the P&L Hard to Trust
QuickBooks can produce a P&L.
That doesn’t mean the P&L is accurate.
The report depends on the transactions behind it.
If the QuickBooks file has uncategorized transactions, duplicate entries, old invoices, unreconciled accounts, personal expenses mixed with business expenses, inconsistent vendors, or income recorded in the wrong place, the P&L may be misleading.
This is why a messy QuickBooks file is more than an annoyance. It can affect the reports an owner uses to make decisions.
A contractor may look at the report and think the business is doing better or worse than it really is.
That can lead to bad decisions.
Maybe prices stay too low.
Maybe hiring happens too early.
Maybe the owner pulls too much cash out.
Maybe a weak job type keeps getting sold because the reports don’t show how thin the margin really is.
If the file is already messy, QuickBooks cleanup for contractors may need to happen before the P&L can be trusted.
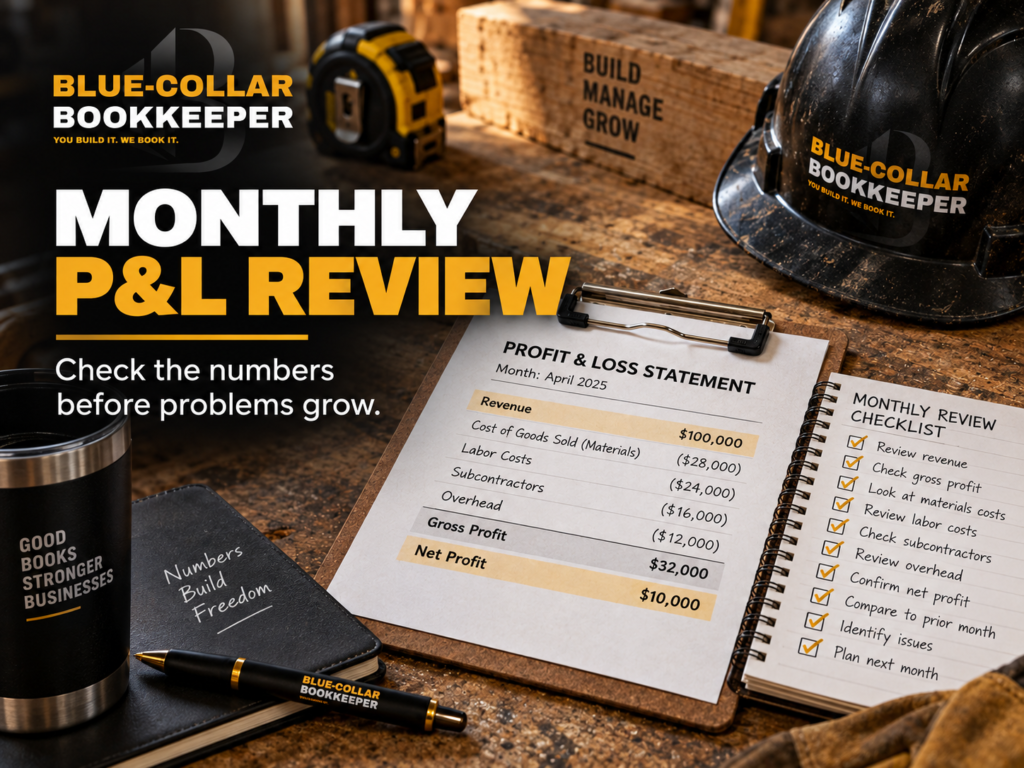
What Contractors Should Review on Their P&L Every Month
Contractors don’t need to stare at reports all day.
But they should review the P&L regularly enough to catch problems before they grow.
A monthly review can help the owner see what changed, what looks off, and what needs attention.
So, what does a P&L show contractors?
Contractors should usually review:
Total revenue
Gross profit
Net profit
Materials
Labor
Subcontractors
Equipment and rentals
Permits and job-specific fees
Overhead
Large unusual expenses
Month-over-month changes
Profit margin
Open invoices separately from the P&L
Bills due separately from the P&L
Cash position separately from the P&L
The point is not to turn the owner into an accountant.
The point is to give the owner clearer numbers to run the business.
That’s where monthly bookkeeping for contractors can help keep reports current and easier to review.
Your P&L Should Help You Make Better Decisions
A P&L should do more than sit in QuickBooks until tax time.
It should help you make better decisions.
A profit and loss report for construction business can help a contractor understand whether pricing needs to change, whether overhead is getting too high, whether labor is running heavy, whether materials are creeping up, whether certain work is worth pursuing, and whether the business is actually producing enough profit for the risk and effort involved.
The P&L should help answer questions like:
Are we pricing jobs correctly?
Are job costs getting too high?
Is overhead eating too much of the profit?
Are we growing profit or just revenue?
Can the business afford another hire?
Are we prepared for taxes?
Are we taking the right kinds of jobs?
Are we building a stronger business, or just staying busy?
That’s the real value of the report.
It shouldn’t just tell you what happened.
It should help you decide what to do next.
Bookkeeping Built for Contractors
The Blue-Collar Bookkeeper helps contractors, trades, and small business owners get reports they can actually use.
That includes monthly bookkeeping, cleanup and catch-up bookkeeping, QuickBooks cleanup, job costing support, cash-flow clarity, and tax-ready books.
The work is built around practical contractor bookkeeping, not generic reports that do not match how the field operates.
The goal is simple.
Cleaner records.
Clearer numbers.
Better decisions.
You build it. We book it.
Profit and Loss for Contractors FAQs
What does a P&L show contractors?
A profit and loss report shows income and expenses over a period of time. For contractors, it can help show revenue, job costs, overhead, gross profit, and net profit, depending on how the books are set up.
Why does my P&L show profit when my bank account is low?
Your P&L may show profit even when cash is tight because profit and cash flow are not the same thing. Customers may not have paid yet, materials may have been purchased upfront, debt payments may have reduced cash, taxes may be coming due, or owner draws may have pulled money from the business.
What is the difference between gross profit and net profit?
Gross profit usually shows what is left after direct job costs. Net profit shows what is left after overhead and operating expenses are also counted. Contractors should understand both numbers because they reveal different parts of the business.
Can a P&L show which jobs made money?
A basic P&L may not show which jobs made money unless job costs are tracked properly. Contractors usually need job costing or project-level reporting to see materials, labor, subcontractors, and expenses by job.
Why are job costs important on a contractor P&L?
Job costs are important because they show what it actually took to complete the work. If materials, labor, subcontractors, equipment, and other job costs are not tracked clearly, the P&L may not show whether jobs are priced correctly.
Can messy QuickBooks affect my P&L?
Yes. A messy QuickBooks file can make the P&L harder to trust. Uncategorized transactions, duplicate entries, unreconciled accounts, old invoices, and inconsistent categories can all distort the report.
How often should contractors review their P&L?
Most contractors should review their P&L at least monthly. A monthly review can help catch cost creep, overhead changes, weak margins, unusual expenses, and reporting problems before they become bigger issues.
Ready to Understand What Your P&L Is Really Saying?
Your P&L should do more than sit in QuickBooks until tax time.
It should help you understand your jobs, your costs, your cash flow, and the decisions that shape your business.
Book a Free Financial Consultation and let’s look at what your books may need next.
We’ll take a look at where your books stand, what may be unclear, and what it would take to get your numbers working for you instead of against you.
Start with a free financial consultation.
You build it. We book it.